China's CXMT Rides Memory Supercycle With $4.9 Billion Quarterly Profit, Wiping Out Years of Losses
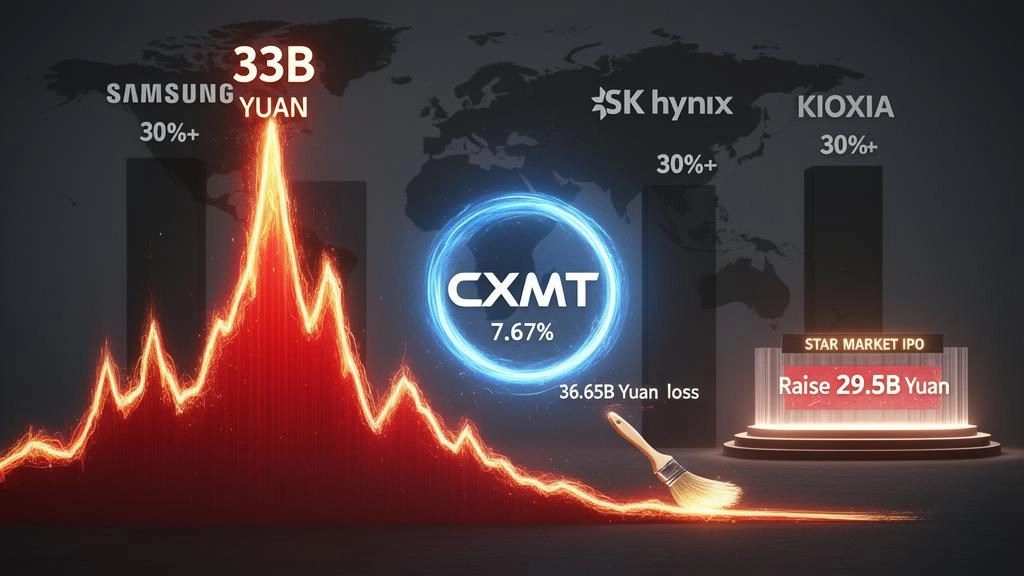
In a powerful convergence of explosive AI computing demand and a memory chip supercycle, CXMT — China's leading DRAM manufacturer — has delivered results capable of redrawing the global memory industry landscape. On May 17, CXMT updated its prospectus for a listing on China's STAR Market, disclosing first-quarter 2026 revenue of 50.8 billion yuan (approximately $7.5 billion), an astonishing 719.13% year-over-year surge. Net profit reached 33.01 billion yuan (approximately $4.9 billion), not only swinging the company to profitability but nearly erasing all historical losses accumulated since its founding in a single quarter.
This level of profitability places CXMT among the top tier of China's A-share listed companies. Its single-quarter net profit of 33 billion yuan surpassed traditional state-owned giants including China Mobile and CNOOC, trailing only PetroChina. Against the backdrop of a global DRAM market long dominated by Samsung Electronics, SK Hynix, and Micron Technology, CXMT's abrupt rise has triggered intense alarm within South Korea's semiconductor industry.
First-half revenue tops 100 billion yuan; profitability timeline dramatically accelerated
According to the updated prospectus, CXMT achieved full-year 2025 revenue of 61.8 billion yuan (approximately $9.1 billion), up 155.6% year-over-year, and posted its first annual profit with net income attributable to the parent company of 1.87 billion yuan (approximately $275 million). The company had previously reported losses of 16.34 billion yuan (approximately $2.4 billion) in 2023 and 7.14 billion yuan (approximately $1.1 billion) in 2024, with cumulative two-year losses reaching 23.48 billion yuan (approximately $3.5 billion).
Entering 2026, as DRAM prices have surged sharply since the second half of 2025, CXMT's performance trajectory has turned nearly vertical. Beyond the 50.8 billion yuan in first-quarter revenue and 33 billion yuan in net profit, CXMT now projects first-half 2026 revenue of 110 billion yuan to 120 billion yuan (approximately $16.2 billion to $17.6 billion), representing more than sixfold year-over-year growth. First-half net profit is expected to range between 66 billion yuan and 75 billion yuan (approximately $9.7 billion to $11.0 billion), with net profit attributable to the parent company at 50 billion yuan to 57 billion yuan (approximately $7.4 billion to $8.4 billion).
This means that despite carrying a cumulative uncovered loss of 36.65 billion yuan (approximately $5.4 billion) as of year-end 2025, CXMT will fully offset all losses accumulated since inception using just its first-half 2026 earnings alone. When the company first disclosed its prospectus last December, it had projected reaching sustained profitability around 2026 or 2027 — a timeline now dramatically accelerated.
Global market share surges; capacity expansion accelerates
The earnings explosion has been accompanied by rapid market share gains. According to research firm Omdia, CXMT's share of global DRAM sales jumped from 3.97% in the second quarter of 2025 to 7.67% in the fourth quarter of 2025. While still dwarfed by the combined 91%-plus share held by Samsung Electronics, SK Hynix, and Micron, CXMT has firmly cemented its position as the world's fourth-largest DRAM player and is gradually narrowing the gap with its larger rivals.
Founded in 2016, CXMT operates three 12-inch DRAM fabrication plants in Hefei and Beijing. The company has adopted a "skip-generation" R&D strategy, having completed mass production across technology platforms spanning its first to fourth generations, with products covering DDR4, LPDDR4X, DDR5, and LPDDR5/5X — all mainstream specifications.
To capitalize on this historic cycle and close the capacity gap with global giants, CXMT plans to raise 29.5 billion yuan (approximately $4.3 billion) through its IPO. The funds will primarily target three major initiatives: technology upgrades for memory wafer manufacturing lines, DRAM technology advancement, and forward-looking technology research. If successful, this would be the largest IPO on the STAR Market since Semiconductor Manufacturing International Corp. (SMIC) raised 53.2 billion yuan (approximately $7.8 billion) in 2020.
AI demand fuels memory supercycle as global players celebrate in unison
CXMT's earnings gusher is no outlier — it is a microcosm of the global memory chip supercycle now underway. Driven by surging demand for AI large-model training and inference, the world's major memory manufacturers are all reporting explosive results.
Japan's Kioxia Holdings (285A.T) also triggered market frenzy with its weekend earnings release. The company posted January-March quarter revenue of 1.029 trillion yen (approximately $6.5 billion), up 2.9 times year-over-year; operating profit hit 596.8 billion yen (approximately $3.8 billion), or 16.1 times the year-earlier figure, handily exceeding the company's own upper guidance of 530 billion yen (approximately $3.3 billion). Even more staggering, Kioxia's April-June quarter guidance projects operating profit of 1.3 trillion yen (approximately $8.2 billion) and net profit surging 47-fold to 869 billion yen (approximately $5.5 billion). The stock gapped up to its daily limit of 51,450 yen on May 18 on heavy buy orders. Kazuyoshi Saito, senior analyst at Iwai Cosmo Securities, noted that stronger-than-expected unit price increases were the main driver of the massive earnings beat, with the market now eyeing annual operating profit targets as high as 5 trillion yen (approximately $31.5 billion).
South Korea's twin giants delivered equally jaw-dropping figures. In the first quarter of 2026, Samsung Electronics posted revenue of 133.87 trillion won (approximately 609.1 billion yuan) — up 69.2% year-over-year — while operating profit skyrocketed 756.1% to 57.23 trillion won (approximately 260.4 billion yuan), surpassing its entire full-year 2025 profit in a single quarter. SK Hynix saw quarterly revenue breach the 50 trillion won mark for the first time, reaching 52.58 trillion won (approximately 239.2 billion yuan), with operating profit of 37.61 trillion won, up 405% year-over-year.
According to data from South Korean corporate research firm CEO Score, the combined operating profit of South Korea's top 500 companies in the first quarter totaled 156 trillion won, with Samsung Electronics and SK Hynix alone contributing 94.84 trillion won — more than 60% of the total. This concentration starkly underscores South Korea's deep economic dependence on the semiconductor sector.
Technology catch-up accelerates; industry landscape faces reshaping
CXMT's rise is transforming the global DRAM market from its long-standing three-player oligopoly toward a four-way rivalry. With ongoing capacity expansion at its fabs in Beijing, Shanghai, and elsewhere, industry estimates project monthly wafer capacity could reach 200,000 to 300,000 wafers in the coming years. Once the capacity buildout is complete, CXMT's global DRAM market share could climb to roughly 15% by 2029, with some capacity already earmarked for HBM3 high-bandwidth memory production.
Facing the rapid catch-up of China's memory makers, South Korea's semiconductor sector is gripped by a sense of crisis. According to South Korea's Maeil Business Newspaper, Samsung Electronics Chairman Lee Jae-yong recently admitted at an internal meeting that it was regrettable the company had failed to widen the gap with Chinese rivals during this memory super-boom. Meanwhile, the technology leak case implicating CXMT — in which a former Samsung employee is accused of leaking core technology to the company — has further intensified the competition for talent and technology between the two sides.
Still, CXMT acknowledged its challenges in the prospectus. On one hand, customer concentration remains high; sales to the top five clients accounted for more than 67% of revenue from 2023 to 2025. While end customers include major technology firms such as Alibaba Cloud, ByteDance, Tencent, Lenovo, and Xiaomi, the over-reliance on a small number of distributors for sales presents structural risk. On the other hand, while gross margins have rebounded sharply from -2.19% in 2023 to 41.02% in 2025, a gap remains compared with industry leaders. The company warned that should macroeconomic conditions deteriorate or the DRAM industry enter a downcycle, product prices and operating performance could face adverse swings.
Regardless, armed with over 100 billion yuan in first-half revenue and an imminent 29.5 billion yuan IPO windfall, CXMT has amassed ample ammunition during this AI-driven memory supercycle to mount a serious challenge against the world's top players.
Once added, BigGo Finance appears first in Google Search Top Stories, so you get the broadest, most up-to-the-minute, and most comprehensive global financial news first.